Digital Lending Onboarding Support: KYC, Cost & ROI
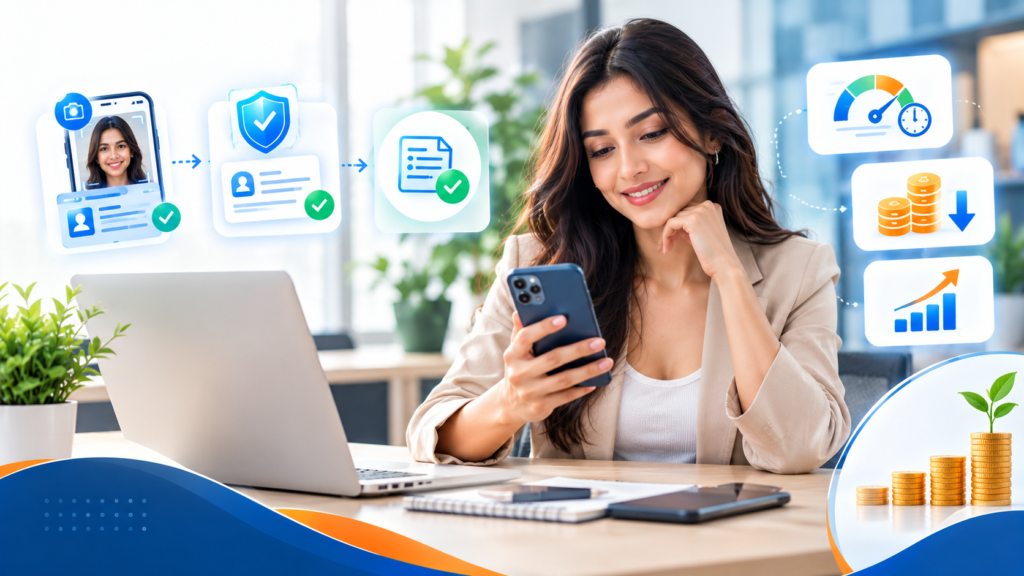
Fintech onboarding is often treated as a product-flow problem: improve the app, shorten the form and reduce clicks. But a customer can complete the digital steps and still fail to activate because they do not understand a KYC request, cannot resolve a verification issue, distrust a communication or do not know what happens next. Fintech customer onboarding call center services add a human-assisted layer to the journey, helping customers progress while giving operations teams visibility into friction and avoidable drop-offs.
This guide explains what onboarding support can include, how to evaluate costs, where outsourced teams can help, and the controls fintechs should require before handing customer interactions to a service partner.
What are fintech customer onboarding call center services?
Fintech customer onboarding call center services are voice and digital support operations that help prospective or newly registered customers move through approved onboarding steps. Depending on the product and the regulated entity’s operating model, this may include explaining the process, resolving application issues, guiding users to official verification channels, following up on incomplete applications and routing exceptions to authorised internal teams.
These teams should guide customers through the process—not bypass identity checks, make credit decisions, collect unnecessary sensitive information or promise approval. The fintech remains responsible for its product, customer outcomes and applicable regulatory obligations.
Which onboarding tasks can a contact center support?
- Application assistance: Explain required fields, document formats and the next step when a customer gets stuck.
- KYC journey guidance: Direct customers to the approved KYC flow and explain status messages without asking them to disclose OTPs, passwords or PINs to an agent.
- Incomplete-application follow-up: Contact customers only under the fintech’s approved consent, communication and suppression rules.
- Technical issue triage: Capture device, app-version or error details through an approved script and route unresolved cases to product support.
- Application status and expectation-setting: Explain what can be confirmed from the authorised system and what requires review by the fintech.
- Language and accessibility support: Help customers understand instructions in supported languages and identify where the digital journey is confusing.
- Escalation management: Route suspected fraud, complaints, vulnerability concerns and unusual requests to the designated team.
The exact scope should be documented in a process map, script, access matrix and escalation matrix before launch.
Why onboarding support matters to fintech growth
Reduce preventable abandonment
When customers stop at a confusing step, a timely and permitted follow-up can help distinguish a genuine lack of interest from a solvable issue. Measure recovery by cohort and reason code; do not assume every abandoned application can or should be recovered.
Improve first-contact resolution
Agents need approved knowledge, clear system permissions and a reliable escalation path. Otherwise, customers repeat information across teams and the contact center becomes another step in the process rather than a way to remove friction.
Identify product friction
Consistent disposition codes can show whether customers are stuck on document upload, unclear eligibility language, OTP delivery, app errors or status uncertainty. Share these patterns with product and risk teams through a regular review—not just a monthly call-volume report.
Scale support without building every capability in-house
An outsourced model may help when application volumes fluctuate, multilingual coverage is needed or an internal team cannot cover extended hours economically. It is not automatically cheaper: transition, training, technology, supervision, compliance oversight and quality assurance all belong in the business case.
How much do fintech onboarding call center services cost?
There is no reliable single price for every fintech onboarding program. Costs depend on interaction volume, average handling time, operating hours, languages, complexity, security requirements, integration work and whether the provider supplies a dedicated team or shared capacity. Request a quote based on your own operating assumptions rather than comparing headline per-agent rates alone.
| Cost driver | What to clarify with providers |
|---|---|
| Delivery model | Dedicated agents, shared team, blended human-and-automation model, or per-interaction pricing. |
| Coverage | Business hours versus extended or 24/7 coverage; weekend and holiday arrangements. |
| Interaction mix | Inbound queries, outbound follow-ups, callbacks, chat and email volumes. |
| Training and QA | Initial certification, refresher training, call sampling, calibration and coaching. |
| Technology and integration | CRM access, dialer or telephony, ticketing, reporting, authentication and implementation charges. |
| Governance and risk controls | Access reviews, audit trails, data handling, incident response, monitoring and vendor oversight. |
| Volume variability | Minimum commitments, ramp-up, peak volumes, shrinkage assumptions and overage charges. |
A practical total-cost model
Compare providers using a monthly total-cost-of-ownership calculation:
Total monthly cost = delivery fees + telephony and platform charges + implementation amortisation + internal oversight + training and QA + integration and reporting costs + expected rework or failure costs.
Then calculate cost per successfully completed, eligible onboarding—not only cost per call. Define “successful” carefully, use the fintech’s verified system of record, and separate agent-influenced outcomes from approvals or decisions controlled by the fintech.
Illustrative example, not MasCallNet performance data: if a program costs ₹4,00,000 per month and supports 2,000 verified completed onboardings, its delivery cost is ₹200 per completed onboarding. If the denominator includes duplicate, ineligible or already-completed applications, the metric will be misleading. Use a consistent cohort and attribution window.
In-house vs outsourced onboarding support
| Model | Best fit | Main trade-off |
|---|---|---|
| In-house team | Low or highly specialised volumes; close product and risk collaboration; strict internal knowledge requirements. | Recruitment, coverage and management capacity must be maintained internally. |
| Outsourced team | Variable volumes, defined repeatable workflows, additional language coverage or faster capacity expansion. | Requires strong vendor governance, controlled access, training and measurable quality standards. |
| Hybrid model | Routine guidance handled externally while exceptions, approvals and sensitive decisions remain with authorised internal teams. | Handoffs and ownership must be explicit or customers can be passed between teams. |
For many fintechs, a bounded hybrid model is worth evaluating first: outsource clearly defined support tasks, retain decision rights internally, and expand scope only after controls and performance are demonstrated.
Security, KYC and regulatory responsibilities
Onboarding support can touch personal and financial information, so security controls must be designed into the operating model. Applicable obligations depend on the fintech’s legal status, product, regulated partners and the activity being outsourced. Obtain legal and compliance review before launch.
- Keep identity decisions with authorised systems and teams. Agents may explain process steps, but should not override KYC outcomes or bypass required verification.
- Minimise data exposure. Give agents role-based access to only the information required for their task. Mask sensitive fields where feasible and prohibit storing customer data in personal notes or unauthorised channels.
- Never request secrets. Scripts should prohibit agents from asking customers to disclose OTPs, passwords, PINs or full payment credentials.
- Log and review access. Maintain access approvals, interaction records, exception logs, periodic access reviews and a documented incident process.
- Control outreach. Define approved contact windows, consent and preference handling, opt-outs, retry limits and complaint escalation.
- Govern the provider. Document permitted purposes, subcontracting, confidentiality, retention/deletion, audit rights, incident notification, continuity and exit arrangements.
The Reserve Bank of India’s Digital Lending Directions, 2025 address digital-lending arrangements and the role of third parties. Regulated entities should assess the provisions applicable to their specific arrangement; outsourcing does not remove the regulated entity’s responsibilities. For personal-data governance, consult MeitY’s Digital Personal Data Protection Rules, 2025 and confirm the relevant commencement timeline and obligations with counsel.
How to measure onboarding support quality
Set a balanced scorecard before go-live. No single metric tells the whole story.
- Contactability: valid contact rate and connection rate for permitted outreach.
- Journey progression: share of contacted applicants who complete the next defined step within an agreed window.
- Resolution: first-contact resolution, repeat-contact rate and time to resolve.
- Quality: script adherence, accuracy, complaint handling and escalation compliance.
- Customer experience: post-interaction feedback and complaint themes, interpreted alongside response rates.
- Risk: unauthorised disclosure incidents, access violations, incorrect promises and policy exceptions.
- Efficiency: cost per resolved contact and cost per verified completed onboarding.
Use quality thresholds and risk measures as guardrails, not as afterthoughts. An increase in conversion is not a success if it comes with misleading claims, inappropriate pressure or control failures.
Implementation checklist for fintechs
- Map each onboarding step, failure reason, system owner and escalation destination.
- Separate customer guidance from regulated decisions, eligibility checks and identity verification.
- Agree scripts, knowledge articles, approved claims, prohibited actions and language requirements.
- Define data access, authentication, recording, masking, retention and incident-reporting rules.
- Set a baseline and agree metric definitions, reporting cadence and quality thresholds.
- Run a controlled pilot on a limited workflow; review exceptions and customer feedback before scaling.
- Agree business continuity, change control, audit access, exit assistance and data deletion requirements.
How to choose a fintech onboarding contact center partner
Ask shortlisted providers to demonstrate their operating controls rather than relying on a generic capability deck.
- Can you show how onboarding scripts are approved, versioned and withdrawn?
- How are agents prevented from requesting OTPs or making unauthorised approval promises?
- What role-based access, masking, audit logging and access-revocation controls are available?
- How are complaints, suspected fraud, vulnerable customers and system outages escalated?
- Can reporting connect contact outcomes to verified onboarding stages without overstating attribution?
- What is included in the price, and what costs extra during implementation or peak periods?
- How will you support audit requests, incident investigations, continuity and a managed exit?
For background on the wider service landscape, read MasCallNet’s guide to contact center functions and operating models and its comparison of contact center vs call center capabilities and costs. Evaluate any provider against your actual process, risk profile and service requirements; the right operating model preserves control while improving the customer journey.
Frequently asked questions
What is included in fintech customer onboarding call center services?
Common tasks include application guidance, approved KYC-process explanations, incomplete-application follow-up, status queries, technical issue triage and escalation. Scope should be documented, and agents should not bypass verification or make decisions reserved for the fintech.
Can an outsourced team perform KYC?
That depends on the regulated entity’s approved process and applicable rules. A support team may guide customers through an authorised workflow, but the fintech should confirm which activities can be delegated and who retains decision authority. Do not assume outsourcing permits a provider to approve or override KYC.
How is onboarding support priced?
Common models include per-agent, dedicated-team, shared-team and per-interaction pricing. Compare the full cost, including implementation, technology, training, quality assurance, management and variable-volume charges.
Does onboarding calling guarantee higher conversion?
No. It can help resolve avoidable friction, but results depend on product-market fit, eligibility, customer intent, journey design and contact permissions. Test with a controlled pilot and a clear comparison group where practical.
Should a fintech outsource all onboarding calls?
Not necessarily. A hybrid approach can keep sensitive exceptions and decisions in-house while a provider handles defined, repeatable guidance and follow-up. Choose based on risk, volume, control requirements and total cost.
What should a fintech include in an onboarding support RFP?
Include scope and exclusions, volumes, languages, operating hours, system access, data controls, training, QA, escalation rules, service metrics, pricing assumptions, audit rights, incident response, continuity and exit requirements.
Discuss your fintech onboarding support model
If application drop-offs, repeat contacts or limited support coverage are affecting your onboarding journey, start by identifying the stages where customers get stuck and the tasks that can safely be standardised. MasCallNet can discuss your contact-center requirements and help you evaluate an appropriate delivery model.
Discuss your contact center requirements with MasCallNet
Editorial note: Regulatory references are provided for orientation, not as legal advice. Confirm current applicability and commencement dates with your compliance and legal teams.
Customer onboarding journey: where support creates value
Map support to the actual digital onboarding funnel rather than treating every unanswered call as a conversion opportunity. A practical fintech customer onboarding process can be measured across these stages:
| Journey stage | Common friction | Appropriate support action | Measure |
|---|---|---|---|
| Registration | Unclear fields, OTP delivery issues or duplicate accounts | Explain the approved steps and route technical failures to the product team | Registration completion rate |
| Application | Confusing questions, eligibility uncertainty or interrupted forms | Clarify instructions without promising eligibility or approval | Application completion rate |
| Identity verification | Document upload errors, failed video flow or status uncertainty | Guide customers to the official verification journey; escalate exceptions | Verification step completion and exception rate |
| Review and decision | Customers expect an instant decision or repeatedly ask for updates | Share only authorised status information and explain next steps | Repeat contacts and status-query resolution |
| Activation | Customer does not know how to access or use the approved service | Provide approved activation guidance and direct customers to official channels | Activation rate within a defined cohort window |
This framework is useful for digital lending customer onboarding, payments, wallets, investment platforms and other fintech products, but the permitted actions differ by product and regulatory status. Agree the process with product, operations, risk and compliance owners before training agents.
Related search topics this guide answers
This guide also addresses six closely related needs: digital lending onboarding support, KYC assistance for fintech customers, loan application follow-up services, fintech customer activation support, digital loan application abandonment and financial services contact center outsourcing. Each phrase reflects a distinct search intent—process guidance, verification support, follow-up, activation, drop-off analysis or vendor selection. Use these terms naturally in relevant sections rather than repeating them mechanically.
Example: calculate onboarding recovery without overstating results
Consider an illustrative pilot with 1,000 incomplete applications that are eligible for follow-up under the fintech’s contact rules. If 300 customers are reached and 90 complete the next verified onboarding step within the agreed window, the observed completion rate among reached customers is 30%. This does not by itself prove the calls caused the completions: some customers might have completed without a call.
For a stronger evaluation, compare similar eligible groups—one receiving the support intervention and one following the existing journey—while controlling for product, acquisition source, application stage and time window where practical. Report the number eligible, attempted, reached, completed and excluded. Do not label all subsequent approvals or activations as agent-generated conversions unless the attribution method supports that claim.
What to include in a fintech onboarding pilot scorecard
- Scope: one product, a defined application stage, eligible contact rules and explicit exclusions.
- Baseline: pre-pilot completion, repeat-contact and complaint rates for comparable applicants.
- Quality gate: approved scripts, monitoring, escalation rules and zero tolerance for prohibited requests such as asking for OTPs or passwords.
- Outcome measures: verified next-step completion, resolution time, customer feedback and cost per completed eligible journey.
- Risk review: complaints, opt-outs, incorrect statements, unauthorised data access and policy exceptions.
- Decision rule: pre-agreed thresholds for continue, modify or stop; expand only when quality and risk remain within limits.
A pilot should answer a business question, not merely demonstrate call capacity. If completion does not improve, review the underlying friction before increasing contact attempts.
Related services and further reading
For a broader view of the fintech support operating model, read MasCallNet’s guide to FinTech customer support outsourcing. If you are evaluating automation alongside human assistance, review the guide to AI call center solutions in India. These resources cover wider delivery choices; this article focuses specifically on onboarding completion, customer guidance and controls around that journey.